Long before fintech apps existed, Nigerians were already building sophisticated systems for saving and investing together. Esusu, cooperative societies, and informal investment circles among friends have moved money through communities for generations — built on trust, discipline, and shared accountability. Halo’s Clubs and Societies feature takes that tradition and gives it modern infrastructure, without changing what makes it work in the first place.
Two Products, Built for Two Different Needs
Halo makes a deliberate distinction between Clubs and Societies, and understanding that distinction is the key to knowing which one fits your situation.
Clubs: Invest With Your Circle
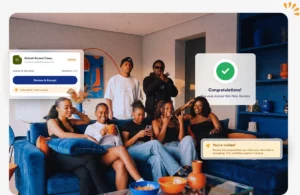
Clubs are built for informal groups — friends, colleagues, alumni networks — who want to invest together socially, without anyone acting as treasurer and without pooling funds. Here’s how it works:
- Invite friends, colleagues or alumni in minutes. Starting a Club takes just a few taps, and anyone in your circle can join with an invite link.
- One shared strategy, funded from each member’s own account. Everyone follows the same investment approach, but no one’s money ever touches anyone else’s account. There’s no pooling and no treasurer, so there’s nothing for any one person to guard or be held responsible for.
- Climb an engagement leaderboard — never ranked by naira. The Club leaderboard tracks participation and consistency, not who has the most money invested. This keeps the experience social and motivating rather than turning saving into a wealth competition.
Because no single person is holding a shared pot, Clubs remove the classic vulnerability of informal group saving: the risk of trusting one person with everyone’s contributions.
Societies: Run Your Cooperative Properly
Societies are built for registered cooperatives, associations, and staff schemes that need real financial infrastructure — not just a shared strategy, but structured contributions, loan facilities, and formal member records. Societies on Halo include:
- Automated contributions with reminders and full records. No more manually tracking who has paid and who hasn’t — the system handles it, with reminders sent automatically.
- Cooperative loans with guarantors and approval flows. Members can request loans through a formal process, complete with guarantor sign-off and disbursement tracking, rather than informal IOUs that are difficult to enforce.
- Digital esusu with clear, visible payout positions. The rotating-payout structure that has worked for Nigerian communities for decades is preserved — but now every member can see exactly where the round stands and when their turn is coming, removing the disputes that paper-based tracking often creates.
- Runs on CBN-licensed, NDIC-insured banking rails. This is the detail that matters most for a cooperative moving real money. Society funds sit within Halo Microfinance Bank Ltd’s regulated infrastructure, not in an informal wallet with no deposit protection.
Why the Regulatory Foundation Matters Here
It would be easy to build a savings-group feature on top of an ordinary payment processor. Halo instead runs Societies specifically on regulated banking rails. For a workplace cooperative with hundreds of members running an active esusu round — potentially moving millions of naira through the system — that distinction isn’t a technicality. It’s the difference between deposits that carry deposit insurance and money sitting in an unregulated wallet with no protection if something goes wrong.
What This Looks Like in Practice
Picture a staff cooperative with 248 members. On Halo, the group’s dashboard shows exactly how many members have paid into the current cycle, the total contributed so far, which esusu round is active out of the full cycle, and who the next payout is scheduled for. A loan that’s already been approved and disbursed shows its guarantors and terms clearly, visible to whoever needs to see it — no spreadsheet, no chasing people for updates.
For a smaller, more casual Club — say, twelve alumni from the same graduating class — the experience looks different but serves the same underlying goal: shared financial discipline without shared custody of funds. Each person funds their own account, follows the same strategy, and can see how consistently the group as a whole is showing up.
Modernizing, Not Replacing
What stands out about Halo’s approach is what it deliberately doesn’t try to change. It doesn’t ask Nigerians to abandon esusu or cooperative societies in favor of some entirely new financial behavior. Instead, it keeps the social structure — the rounds, the guarantors, the shared strategy — and removes the parts that have historically caused these systems to break down: lost records, disputed payout positions, and the vulnerability of pooling cash with one trusted individual.
For a country where cooperative savings culture runs deep, that’s a more meaningful contribution than inventing a new product category from scratch. It isn’t fintech replacing tradition — it’s tradition finally getting the infrastructure it always deserved.
Getting Started
Whether you’re looking to invest casually with friends through a Club, or bring your workplace or association’s existing cooperative onto a properly regulated platform through a Society, Halo’s Clubs and Societies feature is built to meet you where you are — informal or formal, small circle or large membership — without asking you to change how you already save together.